For individuals exiting the traditional workforce in their thirties and forties, Social Security often registers merely as a distant, fuzzy concept in a very far-off future. The objective for early retirees is not securing a modest income stream designed to ease them into their golden years decades down the line; rather, it is building a portfolio that starts working immediately. Furthermore, many in the early retirement community harbor skepticism regarding the government’s ability to maintain long-term solvency and honor its financial commitments decades into the future.

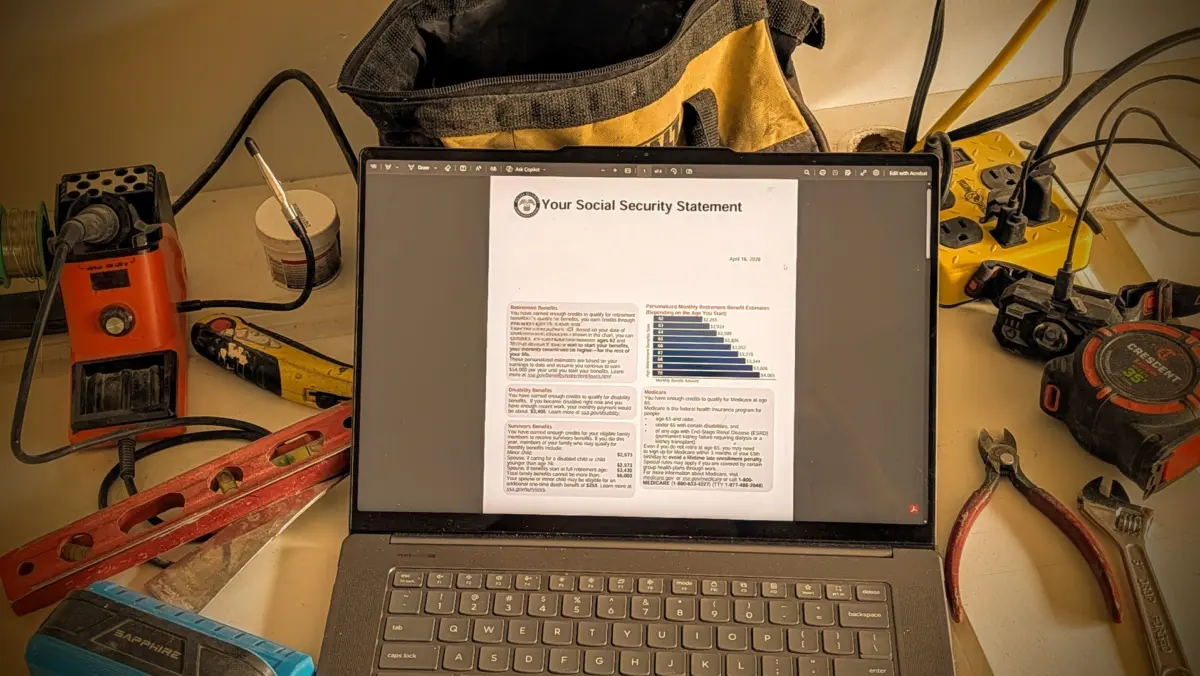
These exact sentiments echoed through the early retirement community years ago, shared by individuals who had successfully engineered their own early exits from the workforce. However, as time passes, perspectives naturally evolve. As early retirees age and observe peers navigating the same life stages, the reality of Social Security re-emerges as a pressing and practical subject. Despite a mountain of conflicting opinions surrounding the program’s future, a closer examination of the underlying mathematics reveals that incorporating Social Security into a retirement strategy boils down to a single, powerful metric: the Net Present Value (NPV) of a future lifetime stream of government payments.
For those without a background in foundational economics, the terminology may sound intimidating, but the concept is easily understood through two distinct financial extremes. For an individual successfully retiring in their thirties, the present value of future Social Security benefits is practically negligible. Even assuming the government fulfills every promise, those payments are situated so far in the future that an independent retirement nest egg must be entirely self-funded to bridge a multi-decade gap.

Conversely, an individual over the age of sixty who has contributed to the system across a lengthy career and maintains a modest cost of living may find themselves eligible for benefits that completely cover their financial needs. In this scenario, the retiree is essentially secure for life, relying on a government program designed to adjust automatically for inflation, thereby minimizing or eliminating the need for further personal capital accumulation.
Between these two extremes lies a complex and illuminating middle ground. While conventional wisdom assumes Social Security remains irrelevant until official eligibility ages are reached, financial analysts note that future benefits can be evaluated as an existing asset that actively reduces the burden of independent saving. Calculating this requires the Net Present Value formula—a standard financial calculation that can be easily executed using modern spreadsheet software or digital analytical tools.

To understand how this calculation functions in practice, financial planners analyze hypothetical scenarios across different age brackets. For instance, evaluating the projected lifetime benefit stream for a young couple starting at age thirty requires several baseline assumptions regarding future payouts and inflation-adjusted discount rates. When running the financial mathematics for a multi-decade stream of income, the resulting figure represents the lump sum required if those payments were to begin immediately.
Applying a secondary discount rate to account for the decades-long delay until official retirement age yields a present-day valuation. In practical terms, this means that a fraction of that calculated value, if invested in a balanced portfolio today and allowed to compound over decades, would grow sufficiently to generate the anticipated monthly payments for a standard thirty-year retirement window. For early retirees, this valuation can be treated as an imaginary addition to a net worth spreadsheet, effectively validating a slightly smaller personal savings target or establishing a comforting margin of safety.

This mathematical framework yields similarly striking insights when applied to older demographics. For a couple at the threshold of early eligibility needing a steady monthly income stream designed to last for three decades, the present value calculation demonstrates the massive capital equivalent required in a traditional investment portfolio to replicate that exact same inflation-adjusted cash flow.
When applied to more typical mid-career scenarios, the implications challenge conventional financial advice. Consider the case of a fifty-five-year-old worker who has experienced setbacks, such as a business failure that depleted a significant portion of personal savings, yet urgently desires an early exit from the workforce. Traditional financial advisors routinely urge such individuals to endure another decade or more of employment to maximize future Social Security benefits, pushing past early eligibility at age sixty-two toward full retirement age or even delaying until age seventy.

However, a rigorous application of the time value of money and investment compounding often challenges the wisdom of delaying retirement solely for incremental benefit increases. For individuals who understand portfolio growth, taking benefits at the earliest possible eligibility age and systematically reinvesting those proceeds into a broad-market index fund can yield substantial compounding advantages. Over a multi-year horizon, an early claimant reinvesting payments can accumulate a capital lead that a peer delaying retirement to secure a slightly larger monthly check may struggle to overcome.
While an individual mid-career worker with depleted savings might not be positioned to retire immediately, the math reveals a surprisingly short runway. Every additional year of working creates a triple financial effect: it adds directly to personal savings, reduces the remaining timeframe for capital to sustain retirement, and continues building future entitlement credits. Once the combined income from personal investments and projected Social Security benefits clears the baseline monthly expense threshold, the transition to retirement becomes mathematically viable.

Ultimately, integrating Social Security into a comprehensive retirement plan alters the psychological landscape of financial independence. The net effect of the program is designed to reduce both financial anxiety and the required duration of mandatory labor. For younger generations and mid-career professionals alike, recognizing future benefits as a present-day financial asset provides a clearer, more grounded perspective on long-term planning, transforming a distant political talking point into a tangible tool for personal autonomy.