For those who manage to tune out financial media, maintaining a long-term perspective is straightforward. But for market watchers, the current cycle evokes memories of past frenzies. Investors worry that while artificial intelligence is undoubtedly a major technological advancement, the market mania surrounding it is moving too fast, setting the stage for a repeat of the dot-com crash of the early 2000s. That particular historical boom launched the early career of online financial commentator Mr. Money Mustache, before the subsequent downturn threatened his job stability and citizenship application.

Addressing these recurring anxieties requires looking beyond daily market volatility. To explore how investors can maintain peace of mind during periods of technological hype and economic uncertainty, financial commentators and retirement advocates have increasingly turned their focus toward human psychology, historical market cycles, and the true drivers of long-term prosperity.
Will the AI Bubble Ruin Our Retirement?
Achieving long-term financial independence often brings comfort, yet the fundamental question remains: how can anyone stay retired and sleep at night with the constant turbulence in the world? News cycles frequently highlight a litany of major concerns, including political instability, inflation eroding purchasing power, escalating national debt, global conflicts, and the looming threat of an artificial intelligence bubble.

Interestingly, these specific worries echo anxieties from past decades. Twenty years ago, in 2006, investors faced a similarly daunting list of concerns. At the time, the world was focused on geopolitical conflicts in the Middle East, surging national debt, inflation, and a housing market bubble that many feared would permanently damage the economy. There were also widespread worries about outsourcing jobs to overseas markets and an impending "peak oil" crisis that predicted dwindling fossil fuel supplies would doom global growth.
Looking back, the subsequent decade brought severe economic turbulence, culminating in the Great Financial Crisis—a historic downturn driven by irrational exuberance in real estate and complex financial leverage. Yet, viewed through the lens of a twenty-year horizon, even that severe recession represents a temporary dip in a long-term upward trajectory. A broad investment in the stock market through those decades still yielded substantial cumulative growth, weathering both the 2008 financial crash and the subsequent market disruption during the COVID-19 pandemic in 2020.

Beyond financial markets, global living standards improved significantly over the same twenty-year period. The proportion of the global population living in extreme poverty dropped from twenty percent to single digits, while infant mortality rates were cut in half. Technological advancements in clean energy drove down the cost of solar panels dramatically, allowing renewable energy to dominate new power generation capacity globally. Meanwhile, electric vehicle adoption surged from near-zero to substantial market share worldwide.
These historical parallels raise a fundamental question about human perspective: whether energy is better spent worrying about an uncertain future or maintaining an optimistic, resilient outlook.

Prosperity Comes from Productivity
Skeptics of the current market cycle often ask whether the present era is fundamentally different. Concerns persist that the United States national debt has reached unprecedented levels, that the artificial intelligence bubble dwarfs the previous housing market bubble, or that advanced automated systems could eventually displace human labor entirely.
Financial media frequently amplifies these fears, often overlooking a core economic reality: true prosperity does not originate from the financial system or the stock market, which ultimately rely on numerical valuations tracked on computers. Instead, long-term prosperity is rooted in productivity.

The fundamentals of capitalism are inherently choppy, subject to wild swings and periodic corrections. However, beneath the surface volatility, real people continue to perform meaningful work and develop tangible innovations. Economic systems and financial markets are human inventions; if a financial system suffers a major correction due to shifting valuations, economic structures have historically adapted through reorganization and continued output.
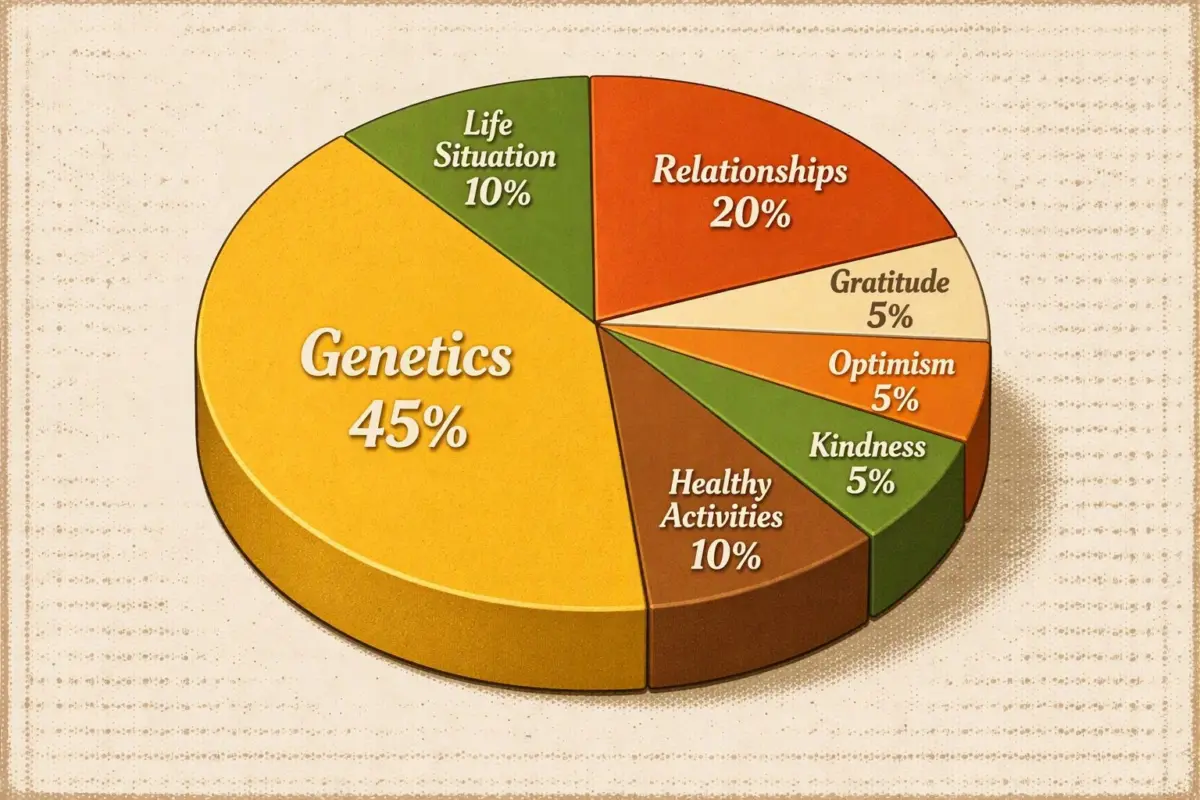
Standard of living, economic growth, and the viability of early retirement strategies all depend directly on sustained productivity improvements. Once a society achieves a certain baseline standard of living, human happiness tends to stabilize in the material dimension. In developed nations, those basic thresholds were surpassed decades ago, shifting the focus of well-being toward personal relationships, community engagement, and individual health choices.

Understanding and Managing Fear
Despite historical evidence showing that market economies recover and adapt, many investors continue to experience persistent anxiety about the future. This background fear is largely a product of human evolution. As a species, humans function effectively as danger detection machines, developing vigilance mechanisms to protect against physical threats and scarcity.
However, modern environments lack the immediate physical predators of early human history, causing the brain’s detection machinery to shift its focus toward abstract worries. Once physical survival and basic food security are assured, anxiety often migrates to social standing, financial comparison, and long-term asset management. In some cases, individuals who achieve significant financial comfort pivot their anxieties toward complex tax strategies, estate planning, or regulatory rules regarding required minimum distributions from retirement accounts.

Combating this persistent fear requires self-awareness and rational evaluation. Examining personal history—such as growing up in households influenced by scarcity mindsets or past economic depressions—can help identify the root causes of financial anxiety. By analyzing the worst-case scenarios associated with financial fears, individuals often realize that potential outcomes are far less catastrophic than anticipated.
Taking concrete action is widely recognized as an effective antidote to fear. Engaging directly with unfamiliar situations builds confidence and fosters resilience, transforming abstract anxieties into manageable challenges. Furthermore, curating one’s daily environment by reducing exposure to sensationalized news media and surrounding oneself with positive, forward-thinking peers can significantly improve mental well-being.

Viewing Technological Change as an Experiment
Approaching life transitions through the lens of experimentation can fundamentally alter how individuals perceive uncertainty. Whether applied to minor lifestyle changes, career shifts, or early retirement, treating life choices as experiments removes the paralyzing weight of perfection.
This experimental mindset applies directly to the current artificial intelligence boom. Rather than reacting to technological shifts with apprehension or doom-scrolling through sensationalized coverage, analyzing the underlying mechanics of AI reveals its potential as a powerful tool for cognitive efficiency.

Artificial intelligence functions essentially as an advanced form of cognitive automation, capable of boosting efficiency, productivity, and broad economic output. Like previous technological revolutions—such as the advent of personal computing and the internet—AI will inevitably displace certain entry-level administrative and technical roles while simultaneously lowering service costs and catalyzing entirely new industries.
While the economic gains from such technologies often concentrate among capital owners and shareholders, the broader integration of automated tools mirrors previous industrial shifts. Ultimately, artificial intelligence represents another variable in a long history of technological progress—an opportunity for adaptation, learning, and continued economic evolution.