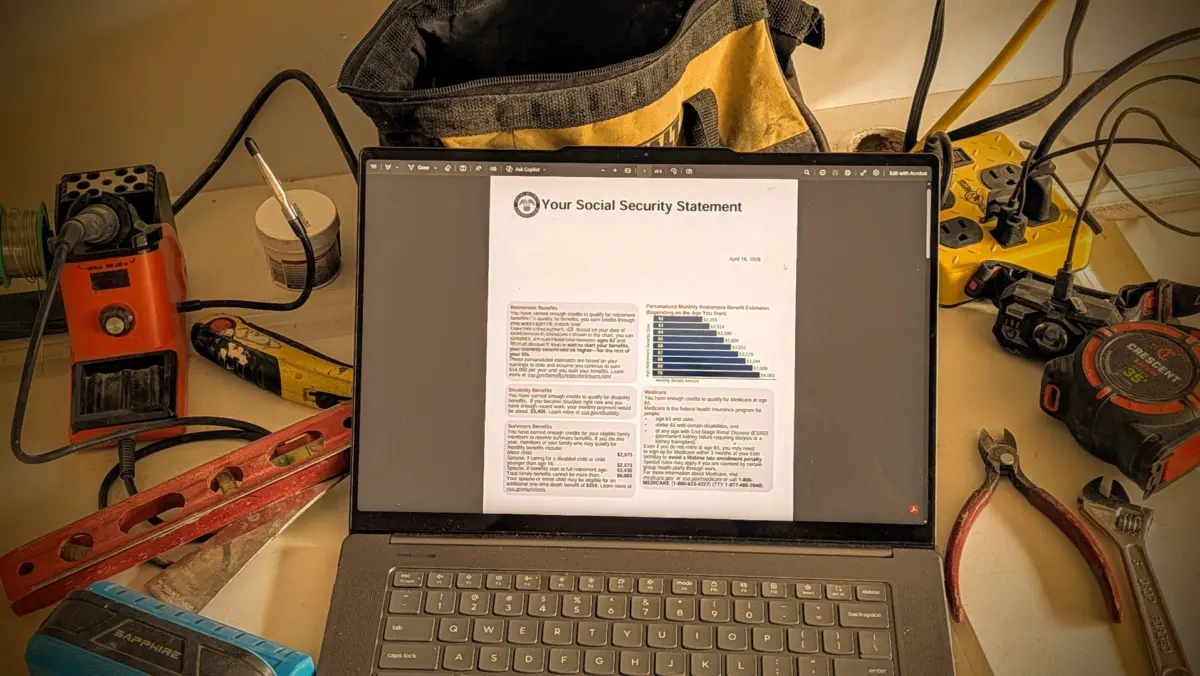
These exact sentiments were shared by veteran early retiree and financial commentator Mr. Money Mustache when he left the workplace in 2005. Yet, as time progresses, personal perspectives tend to shift alongside one’s age. The realization sets in that aging is a universal trajectory, and questions surrounding the mechanics, timing, and true value of Social Security eventually demand attention. Amid a continuous stream of conflicting public opinions, financial experts and retirees alike are forced to reexamine how government benefits integrate into a broader financial independence strategy. When the underlying mathematics are broken down, however, the entire framework becomes remarkably straightforward, hinging on a single financial metric: the Net Present Value of a future lifetime stream of Social Security payments.

While economic jargon like Net Present Value (NPV) might evoke memories of introductory college economics courses, the concept becomes intuitive when examined through distinct financial scenarios. For an individual retiring in their thirties, the present value of future Social Security benefits is effectively negligible. Even assuming the federal government fulfills all existing statutory obligations, those payments remain decades away, necessitating an entirely self-funded retirement portfolio to bridge a thirty-year gap before eligibility begins. Conversely, for an individual over the age of sixty who has contributed to the system across a lengthy career and maintains modest living expenses, projected benefits may completely fulfill their financial requirements. In this latter scenario, an individual is essentially secured for life, as inflation-adjusted government payments remove the necessity for additional personal savings.
Between these two extremes lies a nuanced mathematical middle ground. Rather than treating Social Security as entirely useless until reaching official eligibility ages, retirees can conceptualize the benefit as a tangible asset already embedded in their financial profile—one that diminishes the total volume of independent capital required to achieve financial independence. Calculating this figure involves Net Present Value formulas, which determine the current worth of a future stream of income discounted by an expected rate of return. While formal algebraic equations exist for this purpose, contemporary financial modeling can be executed swiftly using digital calculators, spreadsheet software, or artificial intelligence applications.

To illustrate how this calculation functions across a timeline, consider a hypothetical young couple evaluating their financial position at age thirty. Making reasonable baseline assumptions regarding future inflation, longevity, and a conservative investment growth rate, the nominal value of a thirty-year stream of future income initially registers a high gross figure. However, because those payments will not materialize for more than three decades, discounting that cash flow to account for the time value of money yields a much smaller present-day equivalent. Put simply, if an individual were to invest a relatively modest sum in a growth-oriented index fund today and allow it to compound over thirty-two years, that capital base would expand sufficiently to fund a robust multi-decade income stream matching projected benefit levels, while fully accounting for inflation. Consequently, young retirees can mentally allocate this present-value figure onto their net worth spreadsheets, allowing them to reduce their independent savings targets accordingly.
This financial reality alters traditional retirement calculations, particularly for individuals who find themselves navigating career transitions later in life. Consider the case of a fifty-five-year-old worker who has experienced setbacks, such as a business failure that depleted a significant portion of personal savings, yet urgently desires to exit the traditional labor market. Conventional financial advisory wisdom typically dictates that such individuals must continue working well into their late fifties or sixties to qualify for minimum Social Security benefits, or wait until their Full Retirement Age to maximize monthly payouts.

Running the NPV calculations for various claiming strategies, however, reveals a counterintuitive economic reality. Waiting longer to claim higher monthly benefits does not automatically translate to a higher net present value when factoring in the time value of money and the compounding growth achievable by taking payouts earlier and investing them immediately. For instance, an individual who begins collecting benefits at age sixty-two and consistently reinvests those funds into a diversified equity portfolio can accumulate a substantial financial lead over someone who delays claiming for several years to secure a larger monthly check. By the time the more patient peer begins drawing their higher benefit, the early claimant’s invested capital has compounded to a degree that is difficult for delayed claiming to surpass.
Evaluating these dynamics allows workers approaching traditional retirement age to gauge their proximity to financial independence with greater precision. Every additional year of continued employment generates a threefold positive impact: it increases personal investment contributions, extends the accumulation runway, and enhances future Social Security calculations. Once an individual’s combined portfolio yield and projected Social Security distributions match their targeted monthly living expenses, the transition to retirement becomes viable. Additional strategies, such as discretionary spending reductions or supplemental part-time income, can accelerate this timeline significantly.

Ultimately, the net effect of integrating Social Security into an early retirement plan is a reduction in both financial anxiety and required labor duration. While public discourse frequently centers on the solvency and political future of entitlement programs, demographic realities suggest that protecting benefits for aging voting blocs remains a legislative priority, even if adjustments are eventually targeted toward higher-income earners. For individuals accustomed to managing modest living expenses, projected government distributions frequently cover a substantial portion of annual outlays, functioning as a valuable financial buffer that transforms long-term retirement security.