For those who have tuned out the daily financial drama, the current debate centers on whether the rapid commercialization of AI represents a genuine economic revolution or a runaway speculative bubble. Investors worry that the mania is moving too fast, setting the stage for a historic downturn. This dynamic carries a distinct sense of déjà vu for veterans of early internet financial cycles—an era that initially supercharged early career trajectories before triggering a severe crash that threatened livelihoods and immigration statuses alike.

As questions mount regarding this latest investment cycle, long-time financial commentators and early retirement advocates are taking to conference stages to address the anxieties gripping the public. Following a presentation earlier this month at Camp FI Midwest, industry observers are examining how modern financial panic mirrors past historical busts, and whether the foundational engines of human prosperity are truly at risk.
Will the AI Bubble Ruin Our Retirement?
The psychological weight of retirement planning often manifests as an underlying dread of macroeconomic catastrophe. When individuals look back over two decades of financial history, the anxieties of past eras frequently mirror those of the present day. Twenty years ago, in the midst of the 2006 housing boom, investors wrestled with a different set of existential economic threats. At the time, public discourse was dominated by fears of soaring national debt, persistent inflation, geopolitical conflict in the Middle East, the looming threat of outsourcing white-collar jobs overseas, and a frantic debate over peak oil scarcity.

Yet, despite the palpable dread that preceded the Great Financial Crisis—a severe downturn sparked by irrational exuberance in the housing market and high-risk mortgage leverage—the long-term trajectory of a broad-market investment portfolio tells a remarkably different story. Historical charts illustrate that even through the worst financial crash since the Great Depression, alongside the unprecedented market volatility of the 2020 pandemic crash, patient investors who stayed the course saw their capital appreciate significantly over a twenty-year horizon.
Simultaneously, global socioeconomic indicators registered massive improvements that ran entirely counter to contemporary doom-scrolling narratives. Over a twenty-year period, the proportion of the global population living in extreme poverty dropped dramatically, infant mortality rates were cut in half, and clean energy adoption accelerated as solar panel manufacturing costs plummeted. Solar power generation expanded to represent the vast majority of new energy capacity added globally, while electric vehicle adoption surged from near-zero to substantial market share worldwide.

Despite these demonstrable structural advancements in human welfare, financial media and consumer psychology remain perpetually primed for panic. However, economists and long-term investors emphasize a fundamental reality that is frequently overlooked by market fear-mongers: true prosperity does not originate from the abstract numbers flickering across computer screens in the stock market or financial system. Instead, prosperity stems entirely from productivity.
The Core Driver: Productivity Over Financial Systems
The capitalist marketplace is inherently volatile, prone to sharp fluctuations and cyclical panics. However, beneath the unpredictable waves of the financial system lie real people performing real labor and engineering tangible technological inventions. The concept of an economy or a financial market is fundamentally a human construct. If a system experiences a catastrophic failure driven by negative sentiment, society possesses the capacity to reset the financial parameters and resume productive work—a mechanism deployed successfully during the 2008 financial crisis and numerous historical precedents.

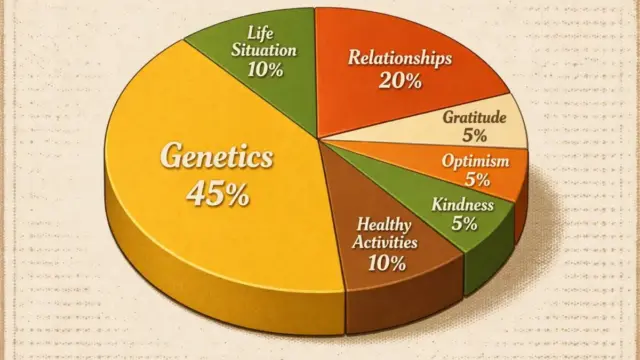
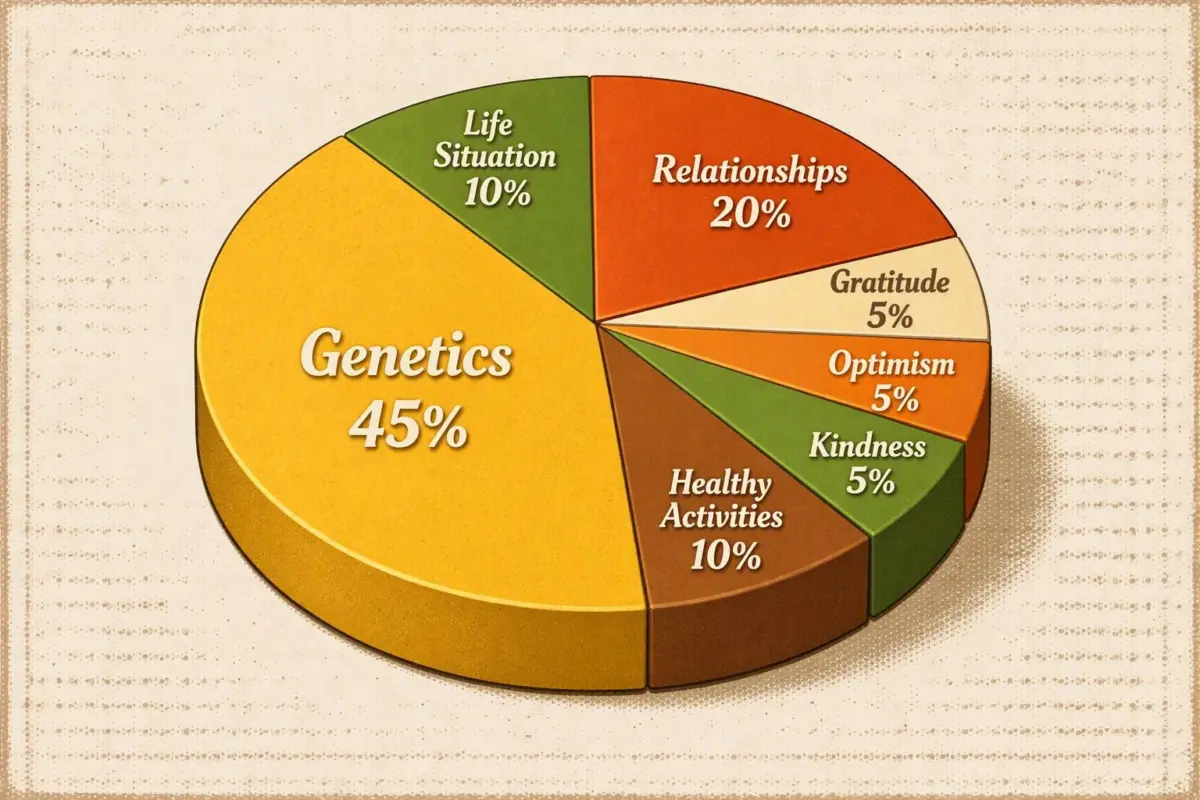
Human standards of living, economic growth, and the viability of early retirement are inexorably tied to high productivity. Once a society achieves a certain baseline standard of living, human happiness tends to plateau along financial dimensions, shifting toward non-financial factors such as personal relationships, community engagement, physical health, and optimistic philosophies.
Yet, persistent background fear remains a pervasive obstacle for many individuals, even those who have successfully achieved financial independence. Human beings evolved primarily as danger-detection machines, an adaptive trait designed to protect ancestral populations from predators, disease, and scarcity. When modern society successfully mitigates these primal threats through advanced civilization, the human brain does not simply turn off its detection machinery. Instead, it continuously shifts the goalposts, finding new subjects for anxiety—ranging from macroeconomic inflation and national debt to neighborhood homeowner associations and tax minimization strategies.

Deconstructing Fear and the Power of Action
Combating chronic financial and existential fear requires a high degree of self-awareness and rational evaluation. Historical analysis suggests that personal anxieties often stem from childhood conditioning, family scarcity mentalities inherited from previous generations who survived historical depressions, or unaddressed psychological trauma. By identifying the root causes of fear and explicitly analyzing worst-case scenarios, individuals can dismantle abstract dread and recognize that their emotional responses are frequently misaligned with objective reality.
Action remains one of the most effective antidotes to fear. By actively confronting unfamiliar situations, individuals build resilience and confidence, transforming abstract threats into manageable realities. When people cultivate the mental, physical, and emotional capabilities to handle adverse circumstances, the perceived danger of an uncertain future diminishes significantly.

Furthermore, managing one’s daily mental diet plays a critical role in psychological well-being. Modern media ecosystems frequently rely on sensationalized, hand-picked disaster narratives designed to provoke panic and engagement. Stepping back from constant news consumption and re-engaging with tangible, productive behaviors—such as physical movement, outdoor activity, and collaboration with optimistic, forward-thinking peers—helps restore mental equilibrium. Adopting an experimental mindset toward major life transitions, whether changing careers, moving to a new location, or entering early retirement, allows individuals to treat uncertainty as an ongoing learning process rather than an existential threat.
Artificial Intelligence as the New Cognitive Frontier
This experimental framework applies directly to the current societal apprehension surrounding Artificial Intelligence. Rather than viewing the rapid advancement of AI through a lens of inevitable doom, technologists and economic analysts increasingly characterize the technology as a powerful new catalyst for efficiency—effectively functioning as a cognitive nail gun.

Like previous technological revolutions, AI promises to dramatically boost productivity, driving long-term economic prosperity by lowering the cost of complex intellectual and analytical services. At the same time, this transition inevitably creates labor displacement, impacting entry-level administrative, software, and financial roles much like past waves of automation. Historically, however, such technological shifts ultimately streamline services and spawn entirely new industries, mirroring the transformative economic expansion unleashed by the internet and mobile computing.
The distribution of rewards from these technological leaps naturally concentrates among the owners of the capital and tools, a dynamic reflected in the recent valuation growth of public equities. For the individual investor, the emergence of Artificial Intelligence represents yet another structural shift demanding deliberate choices. Rather than succumbing to widespread panic, experts suggest utilizing technological change as a trigger for lifelong learning, proactive adaptation, and personal growth.

Ultimately, navigating the uncertainties of modern financial markets and emerging technologies requires looking past short-term volatility and recognizing that the primary obstacles to a fulfilling life are often internal. As financial independence advocates frequently emphasize, the most meaningful milestones, experiences, and securities in life invariably lie just on the other side of fear.