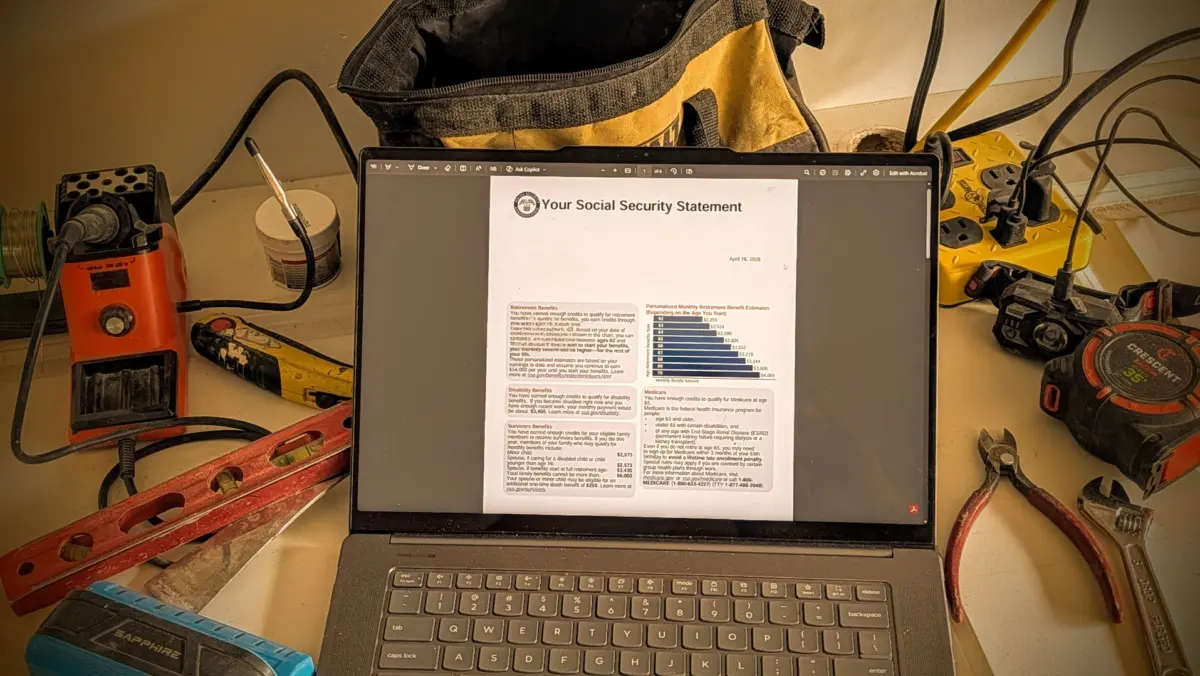
This perspective was precisely what many early adherents held two decades ago. However, time naturally alters personal outlooks, and aging brings a broader awareness of peers navigating the same life stages. Consequently, Social Security re-emerges as a relevant and pressing topic of interest, complicated by an overwhelming volume of conflicting opinions and financial advice.

Yet, when financial analysts strip away the complexities, determining how Social Security integrates into a comprehensive retirement strategy often boils down to a single metric: the net present value of a future lifetime stream of Social Security payments.
While financial jargon can occasionally alienate those without a background in basic economics, the underlying principle is straightforward when evaluated through two distinct scenarios. For an individual aiming to retire in their 30s, the present value of future Social Security payments is negligible. Even assuming the government fulfills all its obligations, those distributions remain decades away, necessitating a fully funded independent retirement portfolio to bridge a thirty-year gap before eligibility begins.

Conversely, for an individual over 60 who has contributed consistently throughout a lengthy career and maintains a modest cost of living, projected benefits can entirely satisfy financial needs. In this latter circumstance, a retiree is effectively set for life, as payments theoretically cover all basic expenses while adjusting automatically for inflation, thereby eliminating the necessity for additional personal savings.
Between these two extremes lies a nuanced mathematical reality. Rather than viewing Social Security as entirely useless until reaching full eligibility, retirees can conceptualize future benefits as an existing asset that reduces the overall burden of independent saving. This valuation is achieved through a net present value calculation. While formal mathematical formulas exist to determine this figure, modern financial planning relies heavily on digital calculators, spreadsheets, or artificial intelligence tools to execute the computation seamlessly.

To understand the practical application, consider a hypothetical young couple evaluating their financial standing at age 30. By establishing reasonable baseline assumptions regarding future earnings and inflation-adjusted payout projections, the initial net present value of a thirty-year income stream yields a substantial preliminary figure. However, because these distributions will not commence for over three decades, a secondary discounting calculation must be applied to account for the time value of money.
The resulting figure demonstrates that a modest investment placed into a growth vehicle today and allowed to compound over thirty-two years would ultimately reach a size capable of generating a steady monthly income stream for the subsequent three decades, accounting for future inflation. Consequently, young retirees can realistically incorporate this estimated present value into their net worth assessments, allowing them to scale back independent savings targets or maintain a more robust safety margin.

This mathematical reality operates consistently over time, offering a useful parallel for individuals at advanced stages of career and retirement planning. For instance, a couple aged 62 requiring a specific monthly income to sustain their lifestyle over a thirty-year period faces a much larger net present value requirement, reflecting the immediate proximity of the benefit distributions. When invested in a conservative income-generating fund, this lump-sum equivalent would produce the targeted monthly revenue while keeping pace with inflationary pressures.
Evaluating these operational extremes clarifies how the strategy applies to more typical scenarios. Consider the case of a 55-year-old worker who experienced significant financial setbacks earlier in life, such as a business failure that depleted a large portion of personal savings, yet still harbors a strong desire to transition out of the workforce. Traditional financial advisors routinely urge such individuals to continue employment well into their 60s to maximize eventual Social Security benefits, pushing past the minimum eligibility threshold of 62 toward full retirement age or even age 70.

A closer examination of the numbers, however, reveals a counterintuitive dynamic rooted in the time value of money and compound interest. Utilizing official online projection tools to evaluate different claiming ages demonstrates that delaying retirement specifically to secure higher monthly benefits later in life may yield a lower net present value compared to claiming benefits at the earliest possible age and immediately investing the proceeds.
If an individual begins collecting benefits at age 62 and channels those payments into an inflation-adjusted index fund, the initial capital begins compounding immediately. Over a five-year period, the accumulated returns and continued contributions create a significant financial advantage that individuals delaying their claim until age 67 struggle to overcome, despite their higher monthly payout.

Integrating this perspective into a comprehensive retirement plan transforms the decision-making process. While an individual in a depleted financial situation might not be positioned to retire immediately, the timeline to financial independence accelerates significantly when factoring in the triple effect of continued part-time earnings, investment growth, and eventual Social Security integration. Once the combined income from personal investments and projected benefits meets targeted monthly living expenses, the transition out of traditional employment becomes viable.
This approach shifts the psychological burden associated with long-term financial planning. The net effect of factoring Social Security into early calculations is a reduction in both financial anxiety and the required duration of formal employment. For households maintaining moderate savings and realistic spending patterns, quantifying future government benefits provides a meaningful boost to overall net worth, functioning effectively as a substantial asset comparable to home equity or conservative bond holdings.

Naturally, discussions surrounding government-backed programs frequently generate skepticism, particularly regarding the potential for legislative reform or benefit reductions. While policy adjustments remain a possibility, protecting retirement security for an aging demographic consistently ranks as a primary legislative priority, making sweeping benefit eliminations politically challenging. More plausible adjustments, such as means-testing that reduces payouts for wealthier retirees, simply indicate that individuals who achieve high levels of personal financial independence may rely less on government distributions regardless of policy shifts.
Ultimately, utilizing digital resources provided by official government portals allows individuals to review their specific earnings history and projected benefits, transforming abstract future policies into concrete data points. By understanding the mechanics of earnings averages, contribution histories, and the time value of money, retirees and prospective retirees can leverage analytical tools—including modern artificial intelligence applications designed for financial research—to construct more accurate, resilient, and realistic long-term financial plans.