
For those who have largely tuned out the financial news cycle to focus on living their daily lives, the detachment is often an enviable position. However, looking at the broader economic landscape reveals a familiar narrative. Investors worry that while AI is undoubtedly a monumental technological advancement, the commercial mania and speculative capital rushing into the sector are arriving too fast and on too massive a scale. This dynamic naturally invites comparisons to past financial manias—a subject of particular resonance for Internet financial commentator and early retirement pioneer Mr. Money Mustache, whose own early career was propelled by the dot-com boom before the subsequent market crash nearly derailed his professional trajectory and citizenship application.
As a veteran voice in the personal finance community, he frequently receives inquiries regarding how to navigate this current investment cycle. To address these persistent anxieties, he recently debuted a presentation at the Camp FI Midwest event, with a polished iteration slated for the upcoming Bogleheads conference in November. Reflecting on more than two decades of early retirement, he recently confronted a familiar question from a concerned friend: how anyone can remain retired, financially secure, and sleep peacefully at night given the state of the world.

When considering contemporary anxieties, the list of global concerns can feel overwhelming. Today’s news feeds are saturated with stories about volatile political figures menacing international stability, persistent inflation eroding household purchasing power, the looming shadow of the AI bubble, a towering United States national debt, and bubbling geopolitical conflicts across the Middle East and Eastern Europe threatening broader escalation. Yet, a historical perspective reveals that these worries are merely updated iterations of anxieties from decades past.
When that same friend posed a parallel question back in 2006, the geopolitical and economic landscape featured entirely different figures and flashpoints. Back then, the world worried about leaders like George W. Bush, Saddam Hussein, and Osama Bin Laden, alongside the grinding conflict in Iraq. Observers similarly fretted over soaring national debt, creeping inflation, and an overvalued stock market—though the speculative villain at the time was the housing bubble rather than AI. Instead of artificial intelligence threatening white-collar employment, the dominant fear was the widespread outsourcing of jobs to India and China. There was even intense public debate over "Peak Oil," with doomsayers predicting that ever-increasing fossil fuel consumption would inevitably collide with dwindling global supplies, triggering societal collapse.

The reality of what transpired over the subsequent two decades challenges the narrative of inevitable doom. Even though the global economy subsequently suffered the Great Financial Crisis—the most severe market crash since the Great Depression, driven by speculative housing exuberance and complex, highly leveraged mortgage-backed securities—the long-term trajectory of the markets proved remarkably resilient. A hypothetical $100,000 investment made prior to that turbulent era still expanded significantly over the long run, comfortably weathering both the financial crisis and the subsequent COVID-19 market shock of 2020.
Parallel to the financial markets, global living standards improved dramatically across several measurable dimensions. Over a twenty-year span, the proportion of the global population living in extreme poverty dropped from 20 percent down to 8 percent. Childhood mortality rates during the first year of life were cut in half. At the same time, clean energy transitions accelerated rapidly as solar panel manufacturing costs plummeted, making solar generation the dominant source of newly added electrical capacity worldwide—equivalent to hundreds of nuclear power plants constructed at a fraction of the historical cost and labor. Meanwhile, pure electric vehicle adoption surged from negligible levels to claim a substantial share of global automotive sales.

These historical comparisons underscore a fundamental economic truth often overlooked by financial sensationalism: long-term prosperity is not fundamentally generated by abstract financial systems or stock market ticker symbols, which essentially represent numerical ledgers computed on servers. True prosperity is fundamentally rooted in human productivity.
The underlying mechanics of capitalism are inherently volatile and subject to dramatic cyclical swings. Beneath the surface turbulence, however, real people continue to perform tangible labor, invent new technologies, and drive meaningful efficiency gains. The concept of an economy or a financial system is itself a human social construct. If a financial system experiences a catastrophic breakdown simply because market participants dislike the arbitrary figures displayed on a screen, society possesses the capacity to reset the parameters and resume productive work—a mechanism demonstrated during the aftermath of the 2008 financial crisis and numerous historical precedents. Every fundamental tool humanity has ever invented to enhance productivity remains intact, providing the foundation for sustained economic growth and the feasibility of early financial independence.

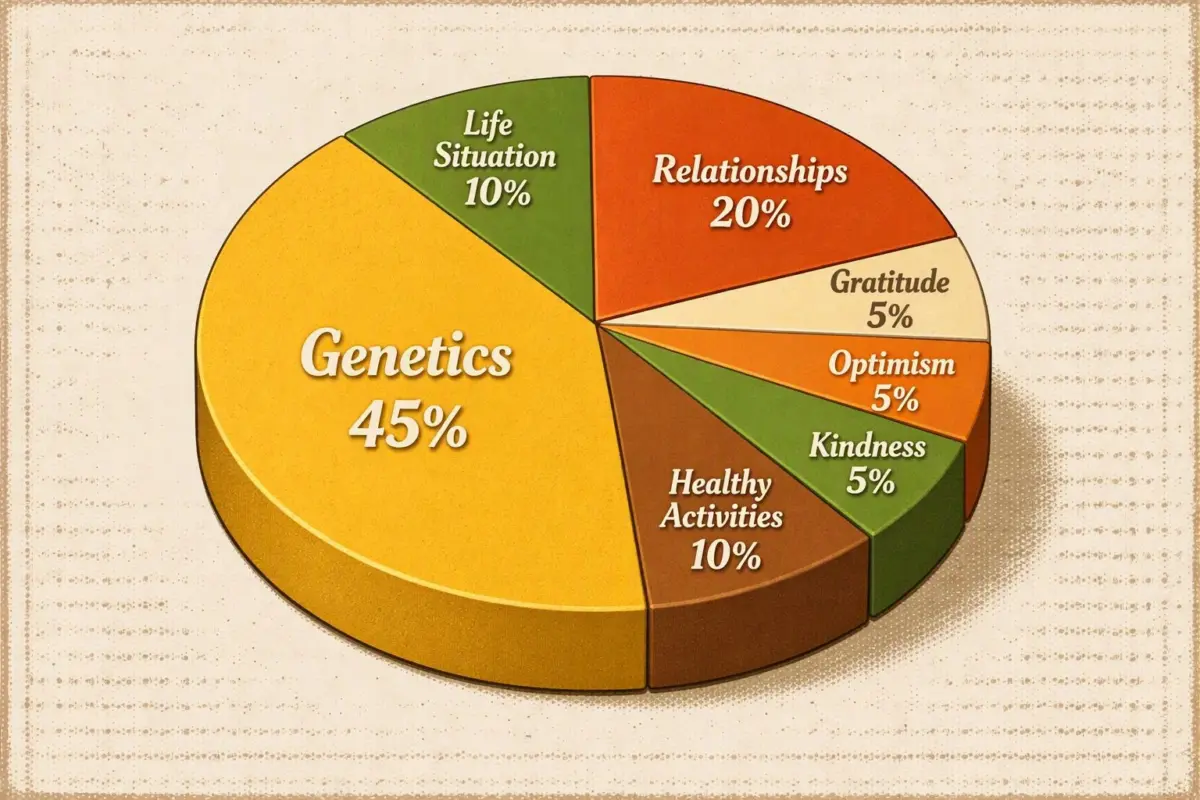
Beyond material prosperity and productivity lies the broader pursuit of human fulfillment. Once a society surpasses a certain threshold of baseline living standards—a milestone achieved by developed nations several decades ago—additional wealth yields diminishing returns regarding overall happiness. Human satisfaction platews within the strictly material dimension, prompting individuals to maximize other aspects of their lives. Psychological research suggests that while genetic predisposition plays a substantial role in baseline happiness, intentional human choices—such as cultivating close interpersonal relationships, practicing gratitude, maintaining an optimistic outlook, and incorporating regular physical activity outdoors—are critical determinants of life satisfaction.
Despite the accessibility of these principles, background anxiety remains a persistent challenge even within financially independent communities. The root of this enduring apprehension often lies in human evolutionary biology. As a species, humans evolved as sophisticated danger-detection machines. This pervasive background fear served as an adaptive mechanism designed to protect ancestral populations from immediate physical threats, predators, and food scarcity.

However, a quirk of this psychological machinery is that when immediate physical dangers are successfully mitigated, the human brain continues scanning the environment for alternative sources of worry. Once scarcity is conquered, individuals begin worrying about social belonging within their tribe. Once financial security is achieved, the goalposts shift toward complex tax strategies, estate planning to secure large inheritances, or navigating mandatory government retirement account distributions once asset thresholds exceed specific limits.
Combating this intrinsic fear requires conscious self-awareness and rational evaluation. Examining personal history helps uncover the root causes of financial anxieties, which often trace back to childhood environments shaped by familial scarcity mindsets or generational trauma inherited from eras like the Great Depression. Recognizing that these fears frequently stem from past psychological conditioning rather than objective present-day realities allows individuals to address the emotional core of their anxiety rather than merely reacting to superficial symptoms.

Taking decisive action serves as one of the most effective antidotes to fear, transforming the unfamiliar into the familiar and building long-term psychological resilience. When individuals develop the mental, physical, and emotional capabilities to handle unpredictable situations, the perceived threats in the external environment lose their potency. Complementing this internal resilience requires curating one’s mental diet by filtering out sensationalized daily news cycles designed primarily to capture attention through fear-mongering narratives. Engaging instead in direct, purposeful activities, maintaining physical health through outdoor movement, and surrounding oneself with optimistic, forward-thinking peers helps realign modern lifestyles with baseline human evolutionary needs.
Viewing major life transitions and economic shifts through the lens of experimentation further neutralizes apprehension. Whether evaluating personal changes such as relocating, shifting careers, or pursuing early retirement, adopting an experimental mindset reframes uncertainty from a source of dread into an opportunity for observation and learning.

Applying this perspective to the contemporary expansion of Artificial Intelligence recasts the technology not as an existential threat, but as a fascinating technological experiment. Viewed through an economic and technological framework, AI functions essentially as a cognitive nail gun—a powerful tool designed to supercharge human efficiency, boost productivity, and ultimately generate broader economic prosperity by lowering the costs of complex intellectual services.
Like every major technological revolution throughout history, AI inevitably creates labor displacement, impacting entry-level administrative, software, and transportation roles while simultaneously catalyzing the emergence of entirely new industries, much like the advent of the internet and mobile computing platforms. While the financial rewards of such productivity gains frequently concentrate among asset owners and shareholders—a demographic that includes many long-term index fund investors—the overarching phenomenon presents a familiar choice. Technology itself remains a neutral catalyst; how individuals choose to respond—whether through fear-driven avoidance or proactive learning, adaptation, and engagement—remains entirely within human agency.