This perspective is common among individuals who achieve financial independence at a young age, but perspectives shift as time progresses. As early retirees age and observe their peers moving through similar life stages, the mechanics of Social Security emerge as an important subject of inquiry. Yet, navigating the topic often means sifting through a dense landscape of conflicting opinions and confusing calculations. According to financial analysts who have deconstructed the problem, the complexity surrounding Social Security can be distilled into a single, highly relevant metric: the Net Present Value (NPV) of a future lifetime stream of payments.

Understanding this calculation does not require an advanced degree in economics, though the core concept relies on evaluating the timeline between retirement and benefit eligibility. For individuals who retire in their thirties, the present value of future Social Security benefits is negligible. Even assuming the government fulfills all current payment obligations, those benefits remain decades away, requiring savers to build a complete, independent retirement portfolio to bridge a gap of thirty years or more. Conversely, individuals who delay retirement until their sixties, having contributed to the system across a lengthy career and maintaining modest living expenses, often find that their projected benefits cover their baseline needs entirely. For this demographic, future Social Security payments can theoretically cover all expenses while adjusting automatically for inflation, reducing the necessity for supplemental savings.
Between these two distinct phases lies a complex middle ground. Rather than treating Social Security as entirely useless until reaching full eligibility, financial planners suggest viewing it as a tangible asset that exists in the present, effectively lowering the amount of capital an individual needs to accumulate independently. This evaluation relies on the Net Present Value calculation, a mathematical formula that can be processed using standard spreadsheet software, online calculators, or modern artificial intelligence tools without requiring manual calculation.

To understand how this functions in practice, financial analysts examine baseline scenarios involving younger demographics. For instance, evaluating the projected lifetime income stream for a young couple at age thirty involves specific actuarial assumptions regarding inflation, wage history, and expected payout durations. When running a traditional NPV calculation for a thirty-year stream of future income, the initial figure often reaches hundreds of thousands of dollars. However, because those payments will not materialize for decades, a secondary discounting formula must be applied to account for the time value of money over the intervening years.
The resulting figure represents a surprising reality: a fraction of that future value, if invested in a compounding asset today, would grow sufficiently large to fund a multi-decade income stream matching the expected government payout, complete with inflation adjustments. Consequently, early retirees can incorporate this present value figure into their long-term net worth projections, allowing them to adjust their personal savings targets downward by a corresponding margin or treat the figure as an additional safety buffer.

This financial mechanism applies equally, albeit with different magnitudes, to individuals closer to traditional retirement age. For a couple at age sixty-two requiring a monthly income stream to sustain them for thirty years, the present value of that future cash flow translates into a substantial capital equivalent. If an individual were required to purchase an equivalent income stream through private investments yielding a steady annual return, the capital required would match the high present value of those guaranteed, inflation-indexed government disbursements.
Examining intermediate scenarios clarifies how this framework assists individuals navigating mid-career transitions or unexpected financial setbacks. Consider the hypothetical case of a fifty-five-year-old worker who experienced significant asset losses during a business failure but hopes to exit the traditional workforce in the near future. Conventional financial advice typically dictates remaining employed until reaching the minimum Social Security eligibility age of sixty-two, or pushing further toward the full retirement age of sixty-seven or seventy to maximize monthly payouts.

However, running the present value calculations reveals a counterintuitive aspect of the system: working longer to secure higher nominal benefits is not always mathematically superior for individuals who understand the principles of investing and the time value of money. When an individual begins drawing benefits at the earliest eligible age and immediately channels those funds into diversified index funds generating historical average returns after inflation, the compounding growth over several years can outpace the incremental gains achieved by waiting for a higher monthly payout bracket. By the time a more patient peer begins drawing a larger monthly check years later, the early claimant’s invested capital and accumulated returns have established a lead that later-stage increases struggle to surpass.
For mid-career workers evaluating their readiness to leave the workforce, the integration of investment income and projected Social Security present value establishes a clearer threshold for financial independence. Each additional year of continued employment provides a triple benefit: it increases personal savings, reduces the timeline until benefit collection, and often replaces lower-earning years in the government’s calculation formula, thereby raising the baseline payout. Once the combined income from personal investments and the discounted value of future benefits aligns with targeted monthly spending needs, the transition to retirement becomes viable.

This perspective alters how individuals across various age brackets can approach their financial planning. For younger generations, the existence of future Social Security benefits serves to reduce psychological anxiety and temper aggressive savings targets, while older workers can factor these guaranteed streams directly into their withdrawal strategies. While public discourse frequently centers on the solvency of the program or potential legislative changes, demographic realities suggest that protecting benefits for an aging electorate remains a paramount legislative priority, making sweeping cancellations unlikely. Even if adjustments are implemented that disproportionately affect higher earners, those individuals are generally positioned to absorb policy shifts without compromising their financial security.
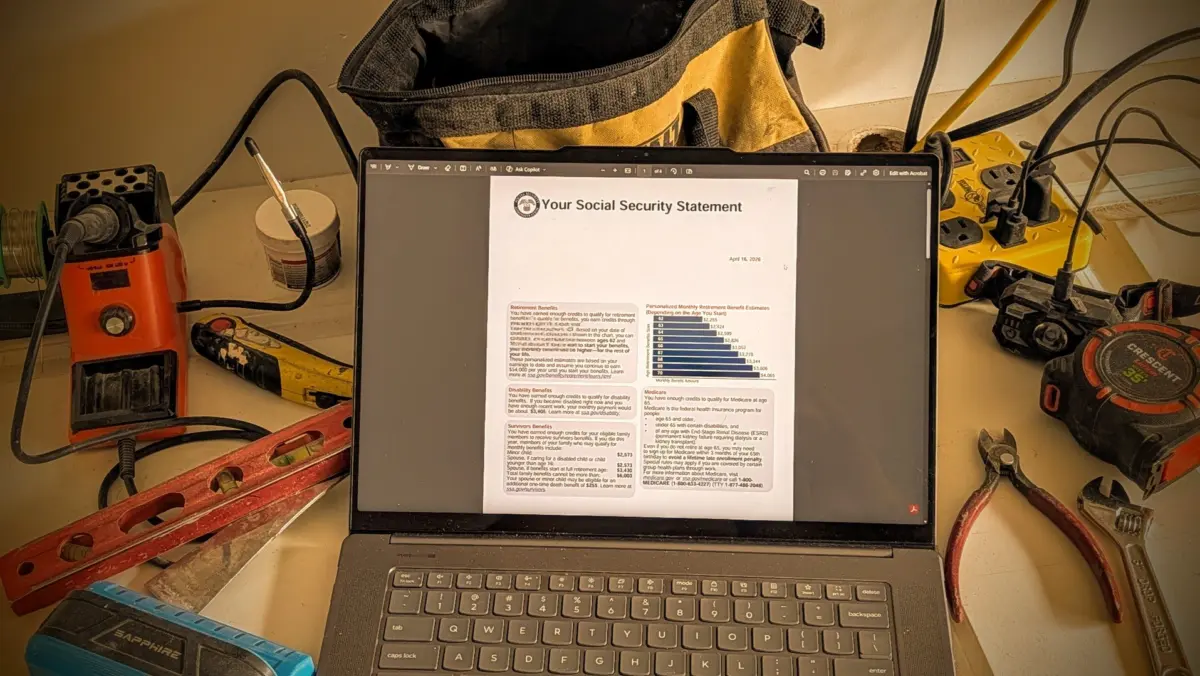
Ultimately, reviewing official benefit statements through online government portals provides workers with the concrete data necessary to run these valuations. Because the system calculates benefits using an average of an individual’s highest thirty-five years of earnings, even those with relatively short careers in traditional employment accrue meaningful baseline entitlements. By recognizing the present value of these future payments, early retirees and traditional workers alike can gain a more comprehensive understanding of their long-term financial standing.